
From 23/5 to 24/7: What an Always-On Equity Market Demands of Issuers and the Community
What an always-on equity market demands of issuers and the community
Roundtable listening guide Panel by panel guide to the September 17 SEC roundtable, with a live scorecard
Watch the roundtable SEC event page, 10 a.m. to 4 p.m. ET on September 17. Recording posted afterwards
Executive summary
Once 23/5 goes live on December 6, 2026, 92% of the hours US equities still sit dark will be the weekend. So the step from 23/5 to 24/7 is not a longer trading day. It is the removal of the weekend, and with it the last scheduled reset the system relies on.
For issuers, that reset is doing more work than most boards realize. The official close, the post-close disclosure window, the Friday evening release and the Sunday night merger announcement all depend on a market that is shut. An always-on market removes each of them.
The plumbing for 23/5 is largely built. NSCC clearing has run 24x5 since June 2026, and the SIPs are approved to run 23x5 from December 6. Nasdaq and NYSE Arca both target the same date. What is not built is anything that works on a weekend: Fedwire and NSS stay closed on Saturdays even after their planned 2028 to 2029 move to six days, there is no weekend clearing, securities lending or corporate actions processing, and the FIX sessions that carry most institutional order flow have no standard way to announce planned maintenance.
Continuous trading gives non-US holders access in their own hours and moves overnight volume into lit, consolidated, surveilled markets. The risk runs the other way: liquidity spread thin across 168 hours, prices set at 3 a.m. on a Sunday by whoever happens to be trading, and issuer disclosure rules written for a market that closes.
Our core asks
Where we are: 23/5 is built, 24/7 is not
The weekday build is almost done. Once 23/5 launches, the market will trade 115 of the week's 168 hours, and 49 of the 53 dark hours will fall between Friday 8 p.m. and Sunday 9 p.m. ET.
View data
| Regime | Trading hours / week | Dark hours / week | Weekend share of dark hours |
|---|---|---|---|
| Core session only (9:30 a.m. to 4 p.m.) | 32.5 | 135.5 | 48% |
| Today’s exchange extended hours (4 a.m. to 8 p.m.) | 80 | 88 | 64% |
| 23/5 (Sun 9 p.m. to Fri 8 p.m., 8 to 9 p.m. pause) | 115 | 53 | 92% |
| 24/7 | 168 | 0 | No dark hours |
The build-out so far
Rules that are already set for 23/5
What the tape actually shows
Until this month the size of the overnight session was a matter of estimate. DTCC put it at about 1% of daily notional and projected 1% to 10% by 2028. On September 10 the staff of the SEC's Office of Analytics and Research filed a memo to the roundtable file that measures the session from CAT rather than from the public tape. It is the first official account of what trades at night.
In August 2026, overnight trading was 0.9% of total NMS share volume, averaging 144.6 million shares a night. That is up 359% from a year earlier and down 27% from July. Both directions matter. The session has grown roughly fivefold in a year, and it still moves enough month to month that no single print should be read as a trend.
Breadth is wider than the headline share implies. An average of 4,208 NMS stocks traded overnight each day in August, 8,335 traded at least once during the month, and 1,814 traded on every trade date. Concentration is severe all the same. The top ten names took 43.4% of overnight share volume and 50.7% of dollar volume, against 10.3% and 21.1% in regular hours, and the overnight and regular top-ten lists overlap by only about four names a day by dollar volume. Whatever trades at night is not a scale model of what trades during the day. The staff also report that foreign accounts were 37% of overnight share volume and 24% of dollar volume, the highest of any session.
The same gap has an hourly version, and it lands on the busiest part of the night. In the staff data presentation accompanying the memo, overnight volume is heavily front-weighted: the first ten minutes is the largest single bucket of the session and the first hour carries 21% of overnight volume. Volume then declines through the night and reaches its smallest bucket between 3:50 and 4 a.m., as flow is redirected to the 4 a.m. open.
Two proposals to change this are live and neither is settled. One would move the maintenance pause from 8 to 9 p.m. back to 7 to 8 p.m., on the reasoning that 8 to 9 is prime trading time in Asia. The other would shorten the pause itself, on the argument that a restart does not need a full hour. Either would put the tape back over the busiest hour of the night, and both are worth watching more closely than the December 6 date itself.
Two ways of counting, two different markets
Share counts and dollar values describe different populations of the same session, and the gap between them is wide enough to change what a reader concludes. Across the three overnight ATSs Sapinover collects from, 2,269 million shares and $104.8 billion traded on the 21 August trade dates. Names under $1 were 35.0% of the shares and 0.15% of the money. Names above $200 were 4.0% of the shares and 46.1% of the money.
View data
| Share price | % of overnight shares | % of overnight dollars |
|---|---|---|
| Under $1 | 35.0% | 0.15% |
| $1 to $5 | 7.6% | 0.43% |
| $5 to $25 | 28.0% | 9.1% |
| $25 to $50 | 9.4% | 7.6% |
| $50 to $200 | 15.9% | 36.6% |
| $200 to $1,000 | 3.7% | 35.0% |
| Over $1,000 | 0.3% | 11.1% |
The same split shows up in single names. One leveraged semiconductor ETF accounted for roughly 11% of all overnight notional on this tape in August, more than QQQ, NVDA and TSLA combined. A share-volume statistic and a notional statistic will therefore support opposite characterizations of the same session. Any rule calibrated to overnight activity, whether a price band, a tick size or a fair access threshold, should state which measure it is calibrated to.
What the night selects
Size is the easy question. The harder one is what the session is made of, and there the difference is not marginal. Measured across the 1,881 names that traded on this tape in August, leveraged and inverse ETFs took 25.9% of overnight dollars against 4.3% of the same names' daytime dollars, six times their day weight, from 311 instruments. In common stock, technology was 74% of overnight dollars against 49% by day. Healthcare, energy, consumer staples and real estate barely register at all.
The sector picture is the same story told in the underlying shares. Reading only common stock, so that the ETF wrappers above do not double-count, the night concentrates into technology and drains almost everything else.
The chart below plots every name in both sessions. If the night were a thinner copy of the day, the cloud would follow a single line. It does not.
The same picture read one name at a time gives the sharpest version of it. Overnight dollar volume as a percentage of a name's own daytime dollar volume ranges from 20% down to 0.003%, a spread of nearly six thousand to one, across names that are all heavily traded in the regular session.
What sits at the top of that list is consistent rather than random. Korea exposure, memory and semiconductors, China-listed names, and metals and crypto proxies are the instruments whose own reference markets are trading while the United States is closed. What sits at the bottom is the domestic core of the day session: large banks, telecoms, broad index funds. That is a statement about what trades, not about who trades it, and the venue data cannot answer the second question.
Narrowness follows from that selection. Ten names carry 51.9% of overnight dollars on this tape and 26.2% of their own daytime dollars, and the overnight curve sits above the regular-session curve at every rank. The staff figure for the regular session across all NMS names is 21.1%, so measured against the whole market rather than against itself, the night is narrower still.
The policy consequence is direct. A parameter calibrated on the day session's composition will not describe the night session. Price bands, tick sizes, fair access thresholds and market maker obligations all assume a distribution of instruments that the overnight tape does not have. As the session grows, the rules written for the day will need to be tested against what the night is actually made of.
Today most overnight flow still runs through ATSs that operate without a consolidated NBBO. That changes on December 6.
What 24/7 means
True 24/7 requires four layers to run continuously: trading venues, consolidated market data, clearing and settlement, and cash movement. From December 6, the first three will run five days a week. The fourth, cash, will not reach even six days until 2028 or 2029, and the Federal Reserve calls that expansion an interim step toward 24/7/365.
What the roundtable weighted
The roundtable ran six hours across a staff data presentation and three panels. Counting the market structure vocabulary across all of it, 42,395 words, gives a rough measure of where the industry's attention actually sat on the day the session was signed off. The word "overnight" was said 200 times, more than twice any other term, and is set aside so the rest can be read.
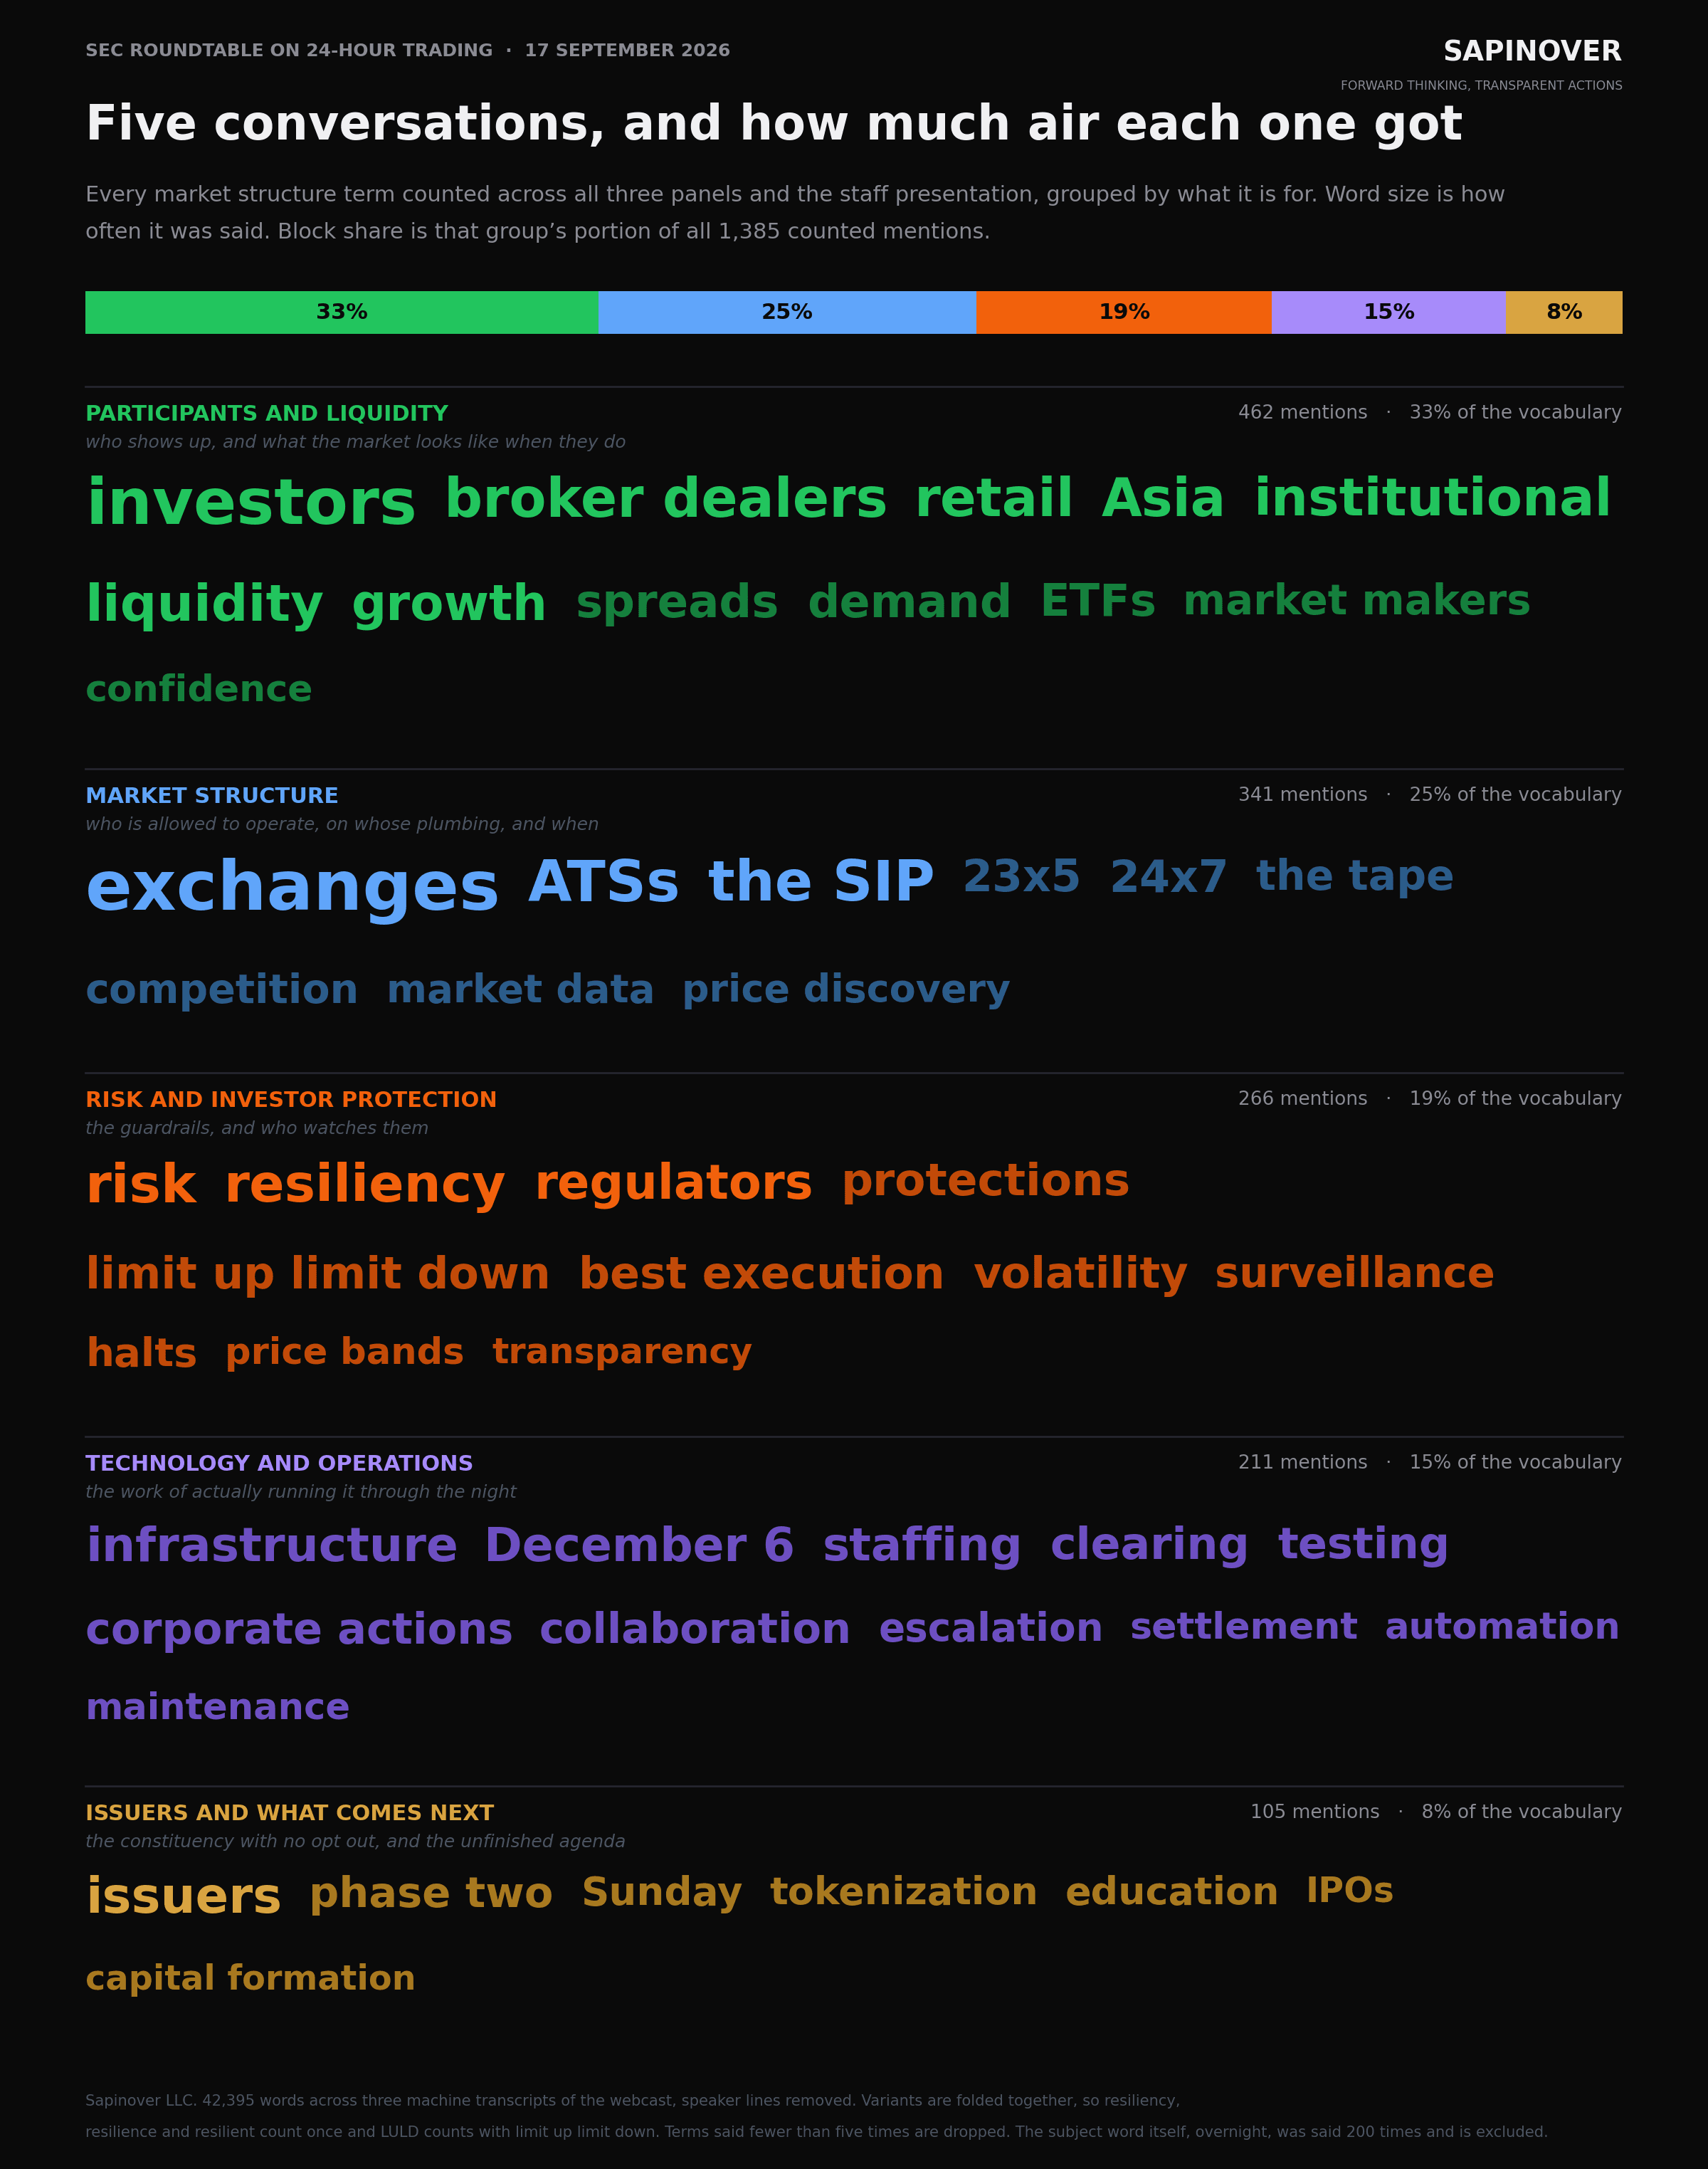
Participants and liquidity took a third of the counted vocabulary, the largest share, which fits a session whose case rests on demand rather than on rulemaking. Market structure took a quarter, and almost all of it is about permission: exchanges, ATSs, the SIP and the tape. Technology and operations took 15%, the work of actually running the thing through the night.
Two shares are worth pausing on. Risk and investor protection drew 19% of the vocabulary for a session that is under 1% of share volume, and inside that group the abstract terms outrank the specific ones: risk and resiliency were said far more often than price bands or halts. And issuers, at 8%, is the smallest group while holding almost every genuinely unresolved question of the day, including tokenization, the weekend, the cash leg and capital formation.
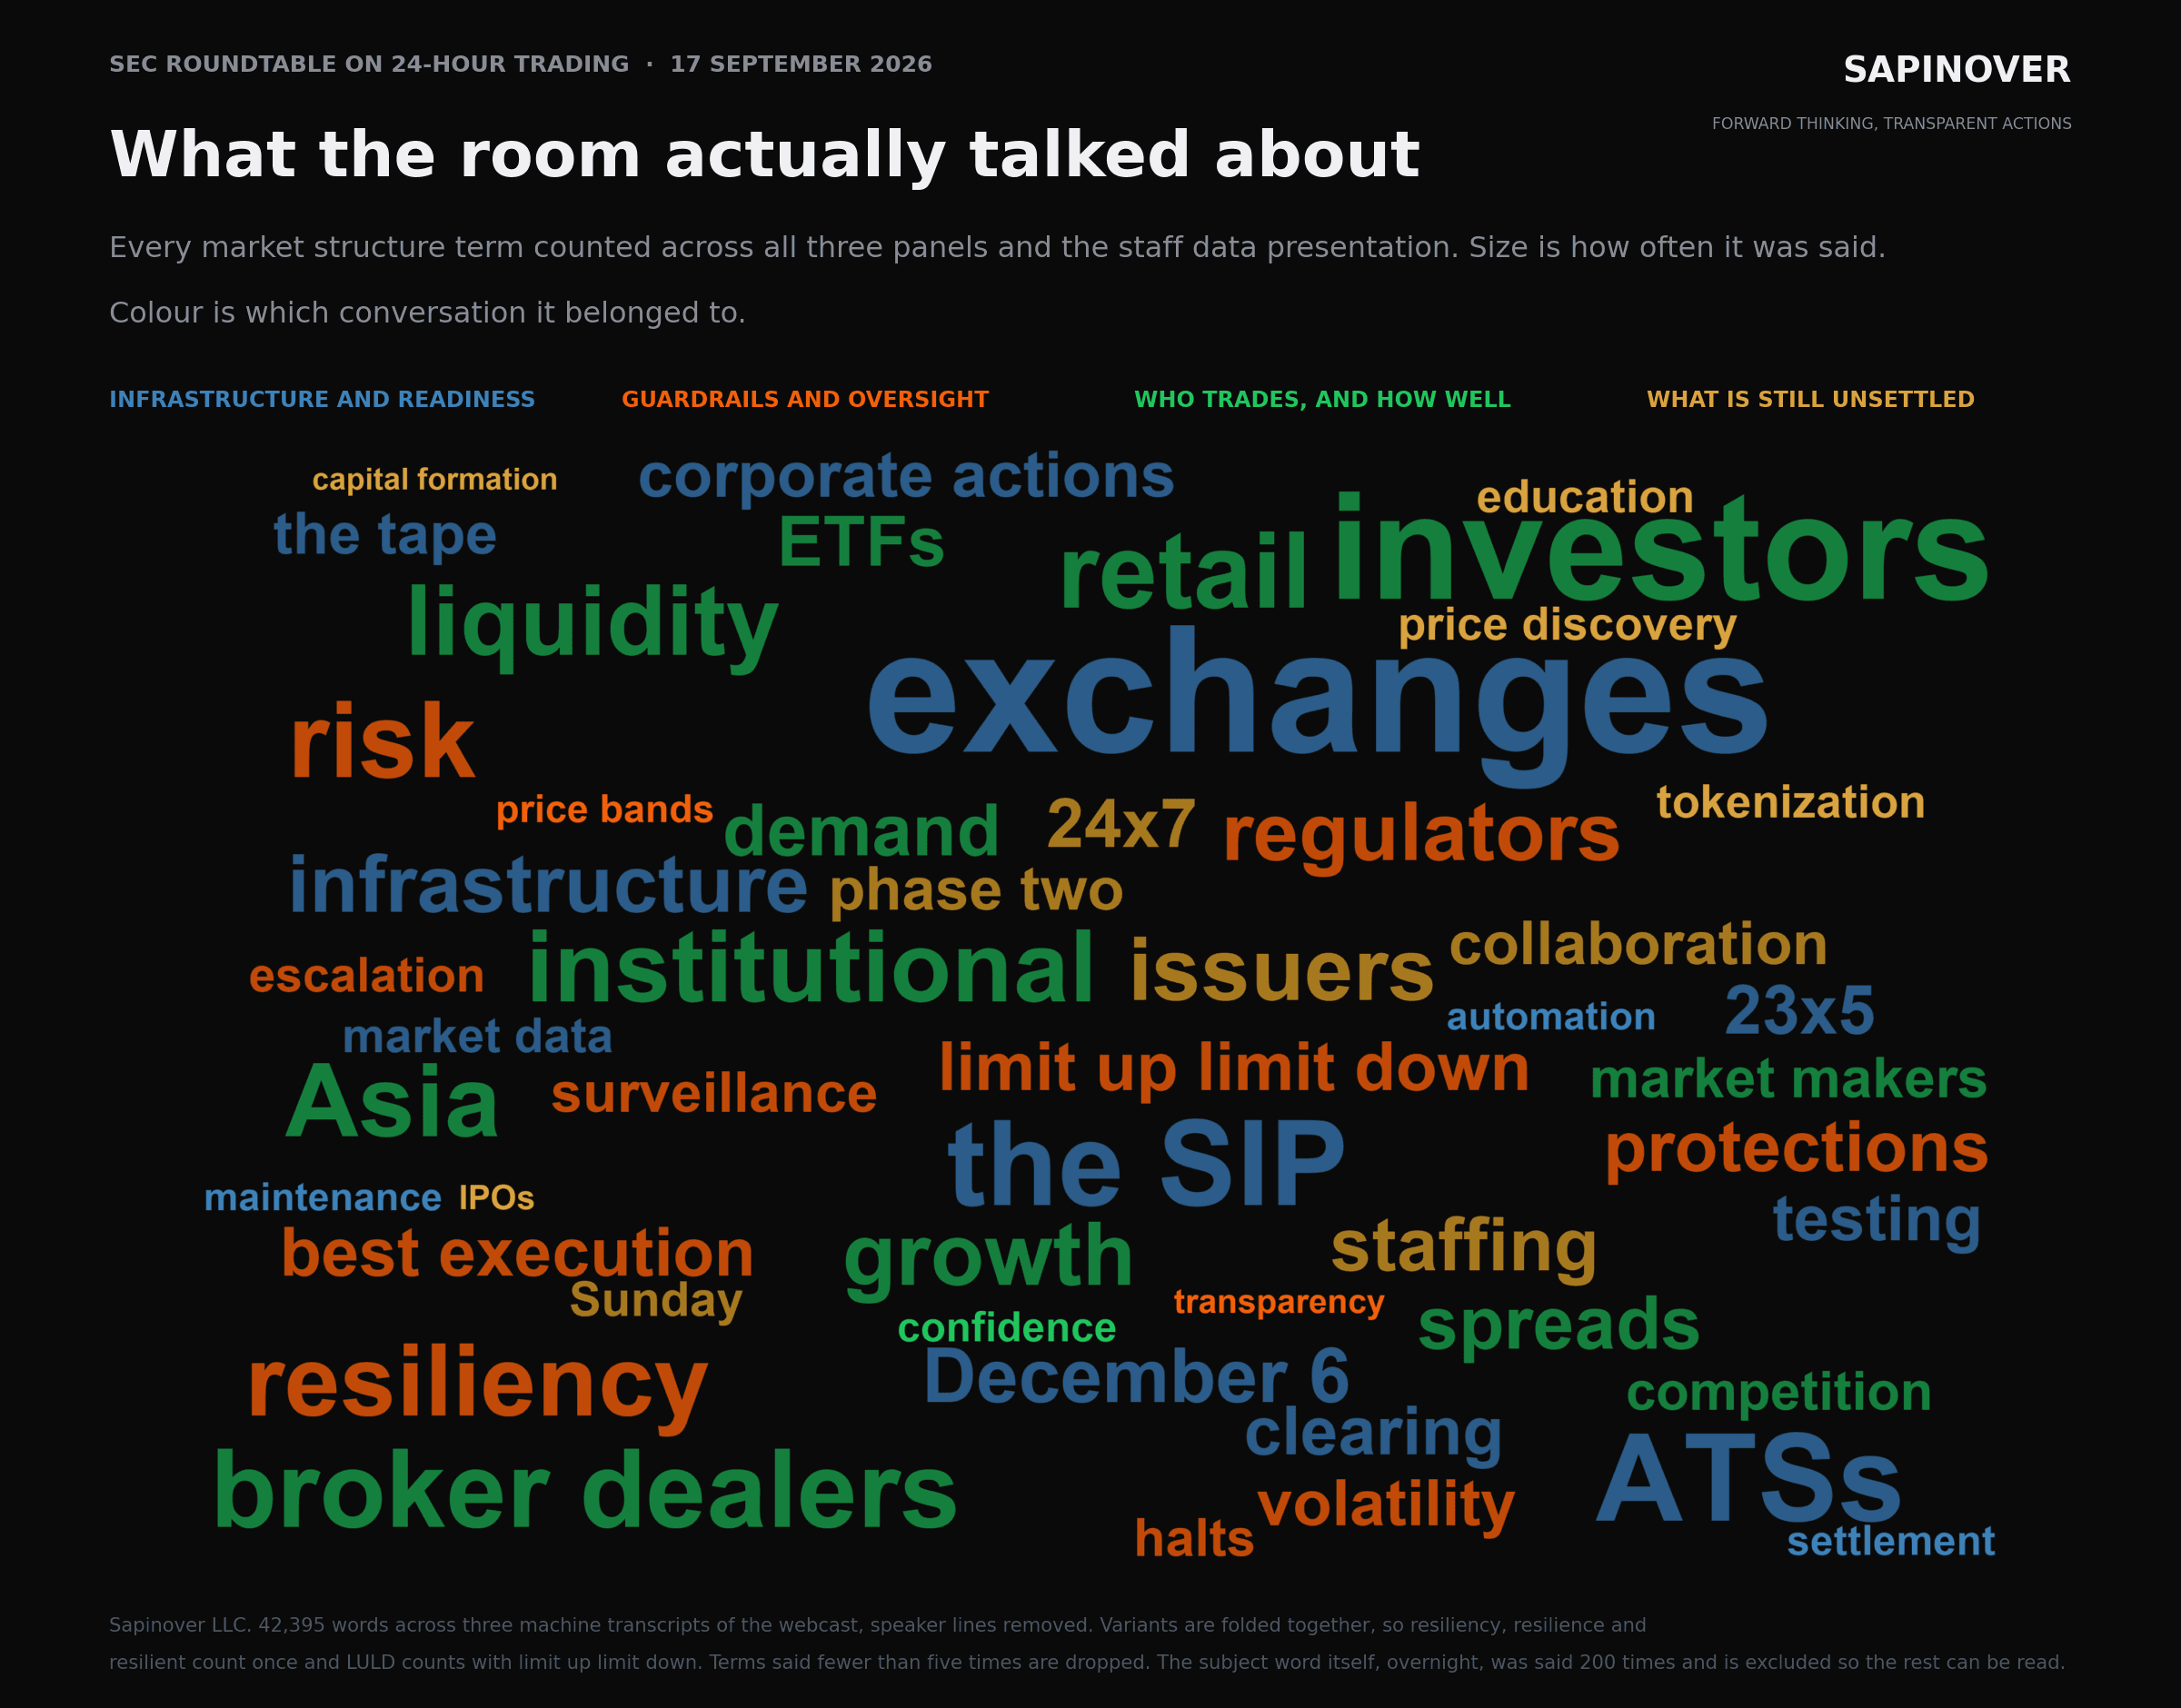
Read term by term, the four largest are exchanges, investors, ATSs and the SIP. The day was spent on who may operate and on whose plumbing. Asia appears 46 times, ahead of liquidity and ahead of every term for a domestic participant type except retail, which is the demand story surfacing in the language rather than in the figures.
The imbalance worth sitting with is the last one. One issuer representative sat in a room of roughly thirty participants, and he opened by reframing the entire exercise: everyone else in the room has a choice about trading 23 hours a day, and issuers do not, because their shares get traded whether they want them to or not. That asymmetry is the subject of the next section.
The issuer lens: a market with no close
Much of how a public company operates assumes the market will close. 23/5 makes that closed period short. 24/7 removes it. The table below shows what issuers lose at each step.
| Issuer function | What it relies on today | Under 23/5 | Under 24/7 |
|---|---|---|---|
| Earnings and material news | Releasing after 4 p.m. or before the open, when trading is thin and prices are off the tape | News hits a lit, SIP-reported market right away. The only quiet times left are 8 to 9 p.m. and the weekend | No quiet time left. Every release is made into a live market |
| Friday evening and Sunday releases | The weekend gives investors time to digest M&A, guidance cuts and leadership changes before trading | Still works | Gone. Holders react to a Sunday deal announcement in a thin Sunday market |
| Official close | The 4 p.m. auction sets index levels, fund NAVs, options settlement, TSR, deal collars and pricing | The 4 p.m. close stays official, but prices keep moving for 23 more hours | The "close" becomes a convention, and Friday’s 4 p.m. price can be stale by Monday |
| Trading halts | Exchange surveillance staff; the 10-minute notice to Nasdaq MarketWatch | Staffed overnight, but thin. Nasdaq resumes trading at 8 a.m. after corporate action halts | Needs weekend surveillance, and halts must reach every venue trading the stock, including tokenized ones |
| Corporate actions | Overnight batch processing for splits, spinoffs, mergers and symbol changes | Squeezed into the 8 to 9 p.m. window. Nasdaq’s mandatory halts now cover eight types of action. NYSE sends corporate action data in the SIP’s start-of-day message, and under 23/5 the trading day starts with the thin 9 p.m. night session | No batch window unless one is designed in |
| Buybacks, ATMs, follow-ons, insider windows | Rules and policies keyed to "trading days," the open and the close (10b-18, Reg M, window policies) | Rules need clarifying for night-session trades | The definitions stop working |
| Shareholder intelligence | Knowing who traded and when, from exchange and custody data | New participants arrive through retail brokers and ATSs | Some trading moves to tokenized wrappers, which are harder to trace back to holders |
Issuers lose the timing of their news
Issuers used to decide when the market heard their news. They are losing that control. Nasdaq's 2015 guidance asks issuers to release news at 4:05 p.m. rather than 4:01 so the closing price can print first. Separately, Nasdaq listing rules require 10 minutes' notice to MarketWatch between 7 a.m. and 8 p.m. For news released outside those hours, notice is due by 6:50 a.m. That schedule assumes nothing trades between 8 p.m. and 4 a.m. From December 6, that assumption is false.
Our expectation is that releases will move into the remaining quiet time: the 8 to 9 p.m. pause and the weekend. 24/7 removes both, so issuers need a new approach built on three things:
- Pre-notification. Notice obligations that apply at every hour.
- Coordinated halts. A standing news-pending halt that works across venues at any hour.
- A realistic Reg FD test. A clear view of what "broad, non-exclusionary" dissemination means when the first reaction may come from an algorithm in Singapore at 2 a.m. Eastern.
The closing price has to stay reliable
The 4 p.m. auction is the one price nearly every contract refers to: index levels, fund NAVs under Rule 22c-1, equity award valuations, TSR performance periods, M&A exchange ratios, convertible settlement and ATM pricing. Under 23/5 it survives, and the market keeps trading around it. Under 24/7 there are two choices. One is to keep a single daily reference auction at a fixed time. The other is to accept that the reference price may be days old by the time a weekend event is priced in. Issuers should push for the first option.
Thin markets create prices that look like news
With limit orders only and 20% static bands, a small order at 3 a.m. can print a large move. Data vendors and news headlines report that print without context. For a mid cap with little overnight liquidity, a thin-session print can move retail margin calls, trigger stop orders and give activists a talking point. Issuers will need overnight price monitoring and a prepared response for moves that do not reflect fundamentals.
More holders, harder to identify
The case for 24/7 is access: non-US and retail holders can trade in their own hours. The cost is visibility. Some of that flow will reach the stock through tokenized wrappers and offshore platforms. There, the link between the token holder and the registered shareholder (voting, dividends, 13F and 13D visibility) depends on the structure of the wrapper, not on any choice the issuer made. Issuers have a direct interest in the terms on which their shares are tokenized, including whether their consent is needed.
Major challenges: the weekend is a settlement problem first
The hardest part of 24/7 is not keeping trading venues open. It is that money, collateral and back-office processes stop over the weekend. A trade can be matched on a Saturday, but nothing that settles it can move until the following week.
| Challenge | Why 24/7 is harder than 23/5 | Primary owners |
|---|---|---|
| Cash and marginGating | Fedwire and NSS reach six days, Sunday to Friday, only in 2028 or 2029. A Saturday margin call cannot be met in central bank money, so clearinghouse exposure builds over the weekend | Federal Reserve, NSCC, clearing banks |
| Settlement calendarGating | T+1 counts business days. Nobody has yet defined whether a Saturday trade date counts, or when it settles. NYSE Arca will already trade on weekday exchange holidays, a small-scale version of the same calendar question | DTCC, SEC, industry |
| Securities lending and Reg SHO | Locates, recalls and close-out deadlines are all tied to settlement days. Weekend short sales have no lending market behind them | Agent lenders, prime brokers, SEC |
| HedgingGating | Single-stock options and most futures are closed on weekends. Market makers quoting on Saturday cannot hedge, so they widen spreads or stay out | Options exchanges, CME, OCC, market makers |
| Resiliency (Reg SCI) | Weekends are when firms upgrade systems, test disaster recovery and reconcile books. A 24/7 market removes that window, and Reg SCI obligations do not pause for a venue that is never offline | Exchanges, SIPs, ATSs, SEC |
| Connectivity (FIX sessions) | Most FIX sessions reset daily or weekly, and that reset is when engines are upgraded and replay logs cleared. The protocol does not require the reset, but it has no standard message to announce planned maintenance, so notice arrives by email and reconnection is often manual | FIX Trading Community, OMS and EMS vendors, brokers, venues |
| Market data | The SIPs rely on a nightly 8 to 9 p.m. maintenance window. 24/7 needs either rolling maintenance or a coordinated weekly pause | SIP operating committees |
| Liquidity and price discovery | About 1% of notional trades overnight today. Spreading that over 168 hours produces thin books, wide spreads and unreliable prints | All venues, market makers |
| NMS protections | Rule 611 order protection does not apply outside regular hours. Best execution benchmarks and Rule 605 statistics for weekend sessions do not exist | SEC, FINRA |
| Surveillance and staffing | FINRA, exchange surveillance, broker operations, transfer agents and IR teams all need weekend coverage | FINRA, exchanges, broker-dealers, issuers |
| Retail protection | Stop orders, margin calls and trading on social media hype play out differently in a thin weekend market | Retail brokers, FINRA |
| Corporate actions and calendar | Record and ex-dates, holiday schedules and batch processing all assume there are closed days | DTC, transfer agents, listing exchanges |
Three of these problems decide whether 24/7 can happen at all: weekend cash, the settlement calendar and weekend hedging. Everything else on the list can be solved with more staff, money and rulemaking. Those three need either new infrastructure or a different settlement model.
The connectivity layer was built around a reset
Almost every institutional order, fill and drop copy moves over a FIX session, and most sessions reset daily or weekly. FIX does not require that reset. Firms do it because it creates a maintenance window and limits how much history a reconnecting counterparty can ask to replay. 24/7 removes the window and leaves three open problems.
The FIX Trading Community is working on this. The protocol itself already supports continuous sessions, so the unresolved questions are operational: how far back recovery is supported, and how a counterparty learns that a session is going down. A 24/7 market needs machine-readable maintenance notices and session failover that every venue and broker supports.
The upside: moving overnight volume into lit markets
About 1% of daily notional already trades overnight, on venues with no consolidated quote. An always-on market moves that volume into a market that is consolidated, surveilled and open to everyone.
Roadmap: measure 23/5, pilot weekends, then scale
The sensible path has four phases, and each should start only when the previous one has produced evidence. The earliest realistic date for broad 24/7 trading in NMS stocks is after Fedwire and NSS move to six days in 2028 or 2029. Even then, Saturday still needs a solution.
| Stakeholder | Tactical: now to mid-2028 | Strategic: 2028 to 2031 |
|---|---|---|
| Issuers | Update disclosure policies, halt playbooks and corporate action checklists for the night session. Set up overnight price monitoring. Revisit insider trading window language that relies on “trading days.” Review 10b5-1 plans, buyback instructions and ATM agreements | Take a position on consent and shareholder rights for tokenized versions of their shares. Build 24/7 IR coverage and a policy on weekend disclosures |
| Listing exchanges | Update the 2015 MarketWatch notice guidance for 9 p.m. to 4 a.m. Publish night-session halt and reopening procedures | Design a cross-venue, any-hour news-pending halt and a fixed daily reference auction |
| SEC | Publish session-level statistics on liquidity, spreads, volatility and erroneous trades. Clarify how 10b-18, Reg M and Reg SHO apply to night sessions | Day 2 rulemaking: define "regular trading hours" and "business day" for an always-on market, and decide how Rule 611 and Rule 605 apply. Set conditions for 24/7 exemptions |
| FINRA | Extend surveillance and CAT review to overnight sessions. Issue retail guidance on thin-market risks | Build weekend supervisory standards for member firms |
| DTCC (NSCC, DTC) | Run 24x5 clearing through the first year of volume. Scale the tokenization service | Define the weekend trade date and settlement calendar. Pilot weekend clearing on tokenized assets |
| Federal Reserve and banks | Deliver six-day Fedwire and NSS | Assess 24/7 cash settlement, including tokenized deposits and regulated stablecoins, as a way to fund weekend margin |
| Market makers and brokers | Staff and risk-manage the night session. Report execution quality by session | Weekend quoting depends on weekend hedging, so work with derivatives venues on extended hours |
| Options, futures and OCC | Study extended hours for single-stock options | Add weekend hedging instruments, at minimum index products |
| Index providers and fund sponsors | Confirm the 4 p.m. close stays the reference price for 23/5 | Define reference prices and NAV practice for weekend events |
| FIX Trading Community, OMS and EMS vendors | Publish guidance on planned maintenance notices and session reset practice for the night session. Support NextExpectedMsgSeqNum(789) on reconnect. Scope 64-bit sequence number support | Standardize session failover, bounded recovery and a machine-readable maintenance notice so sessions can run for weeks without a reset |
Recommendations
The most urgent step is updating issuer rules for the night session before December 6. The most important step is agreeing that 23/5 data, not competition between venues, decides the timing of 24/7.
For the Commission (Day 2)
For exchanges, SIPs and DTCC
For issuers: before December 6
Sources
- SEC Division of Trading and Markets, Office of Analytics and Research: staff memo on overnight trading, September 10, 2026 (File No. 4-913)
- SEC Press Release 2026-83: Agenda and panelists for 24-hour trading roundtable
- Simpson Thacher: SEC approves Nasdaq's 23/5 proposal
- Alston & Bird: Looking ahead to Nasdaq's extended trading hours
- Troutman Pepper Locke: Nasdaq 23-hour proposal approved
- Markets Media: Nasdaq aims to debut 23/5 on December 6, 2026
- NYSE Extended-Hours FAQ v4.0, August 2026
- SIPs receive SEC approval for extended trading hours
- Crowdfund Insider: NSCC rolls out 24x5 clearing
- DTCC: The shift to 24x5 trading
- Federal Reserve Financial Services: Fedwire and NSS expansion of operating days
- CoinDesk: DTCC tokenized securities platform
- crypto.news: SEC regulatory path for 24/7 tokenized stocks
- 24X response letter seeking temporary exemption
- TheCorporateCounsel.net: Nasdaq 23/5 expanded trading halt rule
- Hunton: Nasdaq guidance on post-close release of material news
- ModernIR: Round the Clock
- Sapinover: SIP goes 23x5
- FIX Trading Community: FIX Session Layer
- FIX Trading Community, Continuous Markets Working Group, FIX Continuous Markets: Session Resilience (David Arnold)
This brief describes market structure and public policy. It is observational and does not recommend any security or trading strategy.
Roundtable listening guide Who is speaking on each panel, what to listen for, and a live scorecard for September 17